Eckerö Line advances energy investments as higher costs weigh on group profit

By 2026 Newsletter week 44

Eckerö Line reported a successful summer season, carrying more than 1.5 million passengers on FINLANDIA and FINBO CARGO during January–September 2026. FINLANDIA’s planned three-week docking affected passenger volumes.

Freight business also developed positively, with FINBO CARGO’s Vuosaari–Muuga service now handling 60% of Eckerö Line’s freight, bypassing central Helsinki and Tallinn.

Energy efficiency investments continued:

  • FINLANDIA’s battery system, commissioned in spring, targets a 3% reduction in fuel consumption, equivalent to 500–600 tonnes annually.
  • FINBO CARGO received 120 solar panels, expected to generate around 70 MWh annually and save approximately 15 tonnes of fuel.
  • Rapid charging systems are planned for Helsinki and Tallinn by the end of 2026, enabling battery charging during each port call.

At group level, nine-month revenue declined to EUR 178.0 million from EUR 181.1 million, while operating profit fell to EUR 3.3 million from EUR 21.6 million. Higher fuel and emissions allowance costs were the main factors, alongside FINLANDIA’s docking and preparations for ECKERÖ LINK’s entry into service.

Group passenger traffic fell 5% to 2.36 million and freight declined 1% to 154,665 units. However, February–September freight volumes increased 2%, reaching a record for that period.

Tallink reports higher passenger and freight volumes in Q3

By 2026 Newsletter week 42

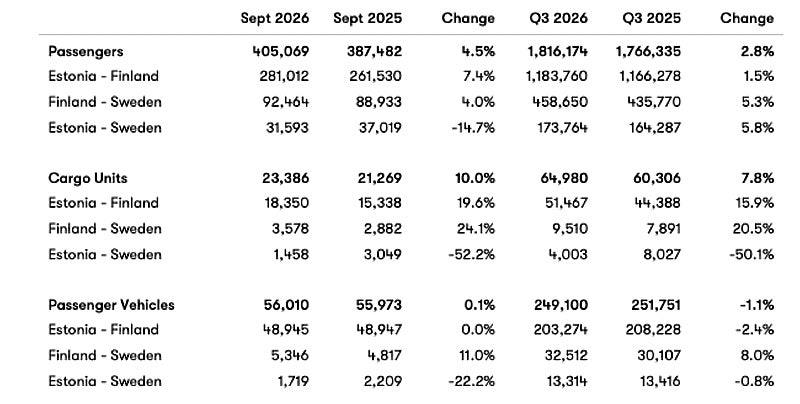
Tallink Grupp carried 1.82 million passengers in the third quarter of 2026, up 2.8% year on year, while cargo volumes increased by 7.8% to 64,980 units.

  • Estonia–Finland: passenger numbers rose by 1.5% to 1,183,760, while cargo volumes increased by 15.9% to 51,467 units.
  • Finland–Sweden: passenger numbers grew by 5.3% to 458,650, with cargo volumes up 20.5% to 9,510 units.
  • Estonia–Sweden: passenger numbers increased by 5.8% to 173,764, but cargo volumes fell by 50.1% to 4,003 units. The comparison reflects the closure of the Paldiski–Kapellskär service following the charter of SUPERFAST IX from 1 May 2026.
  • Passenger vehicles: total volumes declined by 1.1% to 249,100.

For September alone, Tallink carried 405,069 passengers, up 4.5%, and 23,386 cargo units, up 10.0%. Passenger vehicle volumes remained broadly unchanged at 56,010.

https://image.tallink.com/image/upload/grupp/documents/traffic-volumes/2026/2026-09-traffic-volumes-en.pdf

Tallink Grupp Publishes 2024 Q3 Results

By 2024 Newsletter week 43

Q3

  • Passengers:
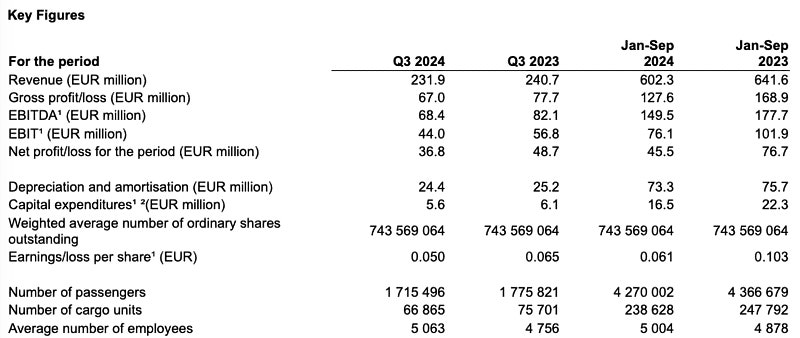
    Tallink Grupp carried 1,715,496 passengers in Q3 2024, a 3.4% decrease from 1,775,821 in Q3 2023.
  • Trips:
    The company operated 1,840 trips in Q3 2024, an increase of 131 trips compared to 1,709 trips in Q3 2023.
  • Revenue:
    Revenue for Q3 2024 was EUR 231.9 million, a 3.7% decline from EUR 240.7 million in Q3 2023.
  • EBITDA:
    EBITDA for Q3 2024 stood at EUR 68.4 million, down 16.7% from EUR 82.1 million in Q3 2023.
  • Net Profit:
    Q3 2024 net profit was EUR 36.8 million, a 24.4% decrease compared to EUR 48.7 million in Q3 2023.
  • Liquidity Buffer:
    At the end of Q3 2024, the company’s liquidity buffer amounted to EUR 107.6 million, compared to EUR 199 million at the end of Q3 2023.
  • Investments:
    Investments in Q3 2024 were EUR 5.6 million, down from EUR 6.1 million in Q3 2023.
  • Loan Repayments & Dividends:
    The company repaid loans worth EUR 27 million and made dividend payments of EUR 44.6 million in Q3 2024.

First Nine Months (1 January – 30 September 2024):

  • Revenue: EUR 602.3 million, a 6.1% decline from EUR 641.6 million in the same period in 2023.
  • EBITDA: EUR 149.5 million, down from EUR 177.7 million in 2023.
  • Net profit: EUR 45.5 million, down from EUR 76.7 million in 2023.

The financial result of the first 9 months of 2024 was impacted by the following factors:

  • Low consumer and business confidence in the home markets as well as mounting geopolitical tensions.
  • The number of vessels on charter dropped from 5 in the beginning of the year to 3 as at the end of the third quarter.
  • Sale of the cruise vessel Isabelle in the first quarter of 2024.
  • Two vessels in lay-up including the cruise vessel Romantika the charter agreement of which was prematurely terminated in September 2023 and MV Superfast IX (formerly Atlantic Vision) the charter agreement of which ended in May 2024.
  • Payment of dividends in the amount of EUR 44.6 million in the third quarter of 2024.
  • Income tax expense on dividends in the amount of EUR 9.2 million was recorded in the second quarter of 2024. In the third quarter of 2024, income tax on dividends was paid in the amount of EUR 4.9 million (EUR 4.3 million of the dividend tax expense was offset by prepaid income tax).
  • Repayment of long-term loans in the amount of EUR 59.5 million.

CEO’s Outlook (Paavo Nõgene):
Despite challenging market conditions and the fragile economic environment, Tallink Grupp’s third quarter results are strong. With two vessels suspended, the company has still managed to deliver confidence-inspiring results. The company remains lean and aims to reinstate its regular dividend payments in 2025, barring any unforeseen disruptions during the remainder of the year.

For a more detailed report: Tallink Newsroom

Port of Gothenburg Q3: Containers Up, Ro-Ro Down

By 2023 Newsletter week 44

The Swedish purchasing power remains low in the wake of economic downturn, resulting in reduced container imports. However, overall container handling in the Port of Gothenburg is increasing as the Swedish export industry continues to thrive, with the forestry sector leading the way.

Intra-European Ro-Ro traffic decreased by 6% during the first three quarters of the year. Like the container segment, import volumes have gone down, but the upturn on the export side has not compensated to the same extent as in the container segment.

Strong Performance for Attica Holdings S.A. in challenging times

By 2021 newsletter week 48

Consolidated revenue

Q3 +30.58% EUR 148.31 million

9M +17.32% EUR 270.50 million

EBITDA

Q3 +27.80% EUR 47.11 million

9M +10.18% EUR 42.74 million

EBIT

Q3 EUR +35.85% 33.34 million

9M EUR +29.40% 4.31 million

Consolidated Profit after taxes

Q3 EUR +32.74 million (12.14 million)

9M EUR loss 1.31 million (loss 28.81 million)

Outlook

Traffic volume will be affected by the evolution of the pandemic and any additional restrictive measures that may be imposed on the movement of passengers.

Marine fuels cost has significantly increased, burdening the operating expenses of companies. During Q3, the Group’s marine fuel costs increased by 74.5% compared to the corresponding period last year.

ΑΝΕΚ Lines : a good summer, soaring bunker prices

By 2021 newsletter week 48

Gradual recovery of economic activity = increase in traffic = improvement of ANEK’s operational results.

Q3 (summer high season) saw a significant recovery compared to last year.

Sharp rise of bunker prices absorbed the benefit of the good season.

9M +18% turnover EUR 114.2

Q3 +35% turnover EUR 56.0 million

9M EUR 12.4 million (7.7 million in the first nine months of 2020)

Q3 EUR 13.1 million (10.0 million)

9M EUR profits of 4.2 million (losses of 0.7 million in the first nine months of 2020)

Q3 profits of 10.3 million (profits of € 7.2 million)

The upward trend of traffic in all categories of transport project of the Group continues in the months of October and November. However, fuel prices remain fluctuate to very high levels overburdening operating costs.

Fjord1 expects continued strong demand for its services

By 2021 Newsletter week 47

Fjord1’s first nine months and third quarter 2021: Safe and stable operations

Q3

  • -4% Revenue, NOK 758 million. The reduction is attributable mainly to the phasing out of the Molde-Vestnes ferry contract.
  • -18% EBITDA, NOK 276 million
  • The EBITDA margin decline to 36% from 43% mainly reflects higher fuel costs and higher maintenance cost than in same quarter last year.
  • Investments amounted to NOK 289 million, mainly for purchase of a new vessel.

First nine months

  • -5.9% Revenue NOK 2,157 million
  • -14.5% EBITDA NOK 663 million
  • EBITDA-margin of 31% (34)
  • Investments were NOK 531 million for the first nine months, which represented 60% reduction from the same period in 2020, when investments in the newbuilding and electrification programme peaked.
  • Net interest-bearing debt (NIBD) stood at NOK 5,274 million as per 30 September. The company has lower investment commitments going forward and will use operating cash flows, proceeds from infrastructure sales, and NOx compensation for electric vessels to continue to reduce debt.

Outlook

Fjord1 is confident that there will continue to be a strong demand for safe, environmentally friendly, and reliable transport in coastal regions in the future. Fjord1 assesses new tender opportunities in the Norwegian market on an ongoing basis, as well as opportunities outside of Norway.

Fjord1’s strong contract portfolio is worth NOK 21.8 billion through 2034, excluding options and index regulation, which offers a solid platform for profitable growth.

The company had net interest bearing debt of NOK 5.3 billion at the end of September 2021, down from NOK 5.8 billion at the end of September 2020. The company plans for a lower investment level going forward and expects the main part of the cash flow from operating activities and proceeds from the sale of infrastructure assets to be used to reduce interest-bearing debt further.

Click on the cover, access the download page of Fjord1, and download the report

Piraeus Port Authority Q3 2020 Key Financial Figures

By 2021 Newsletter week 4

January – September

  • -10.79% turnover 99,380,554
  • -20.6% gross profit
  • -13.47 EBITDA
  • -31.37% EBIT
  • -19.16% Consolidated Profit before taxes
  • -19.16% Consolidated Profit after taxes

Q3

  • -19.47% turnover 32.878.031
  • -33.2% gross profit
  • -30.04% EBITDA
  • -37.66% EBIT
  • -39.51% Consolidated Profit before taxes
  • -39.51% Consolidated Profit after taxes

PPA’s investment activity continues based on its business plan and within the third quarter of 2020 investments that were made amounted to 4.1 million euros

PPA’s overall traffic figures in 2020 (5,436,797 TEU), despite the pandemic, presented a reduction of 3.7% compared to 2019 (5,648,054 TEU), which is an excellent performance compared to other European ports with higher losses.

FERRY SHIPPING

By 2020 Newsletter week 50

ANEK LINES Q3 2020 Key Financial Figures

During the first nine months (2020), traffic volumes of the ANEK Group vessels dropped by 50% for passengers, by 44% for private cars and by 8% for freight units.

Respectively, in Q3 (2020) traffic volumes decreased by 48% in passengers, by 38% in private cars and by 6% in freight units.

First 9 months of 2020 in EUR ,000 (same period in 2019)

  • Turnover: 97,004 (138,076)
  • Gross Profit:  13,893 (36,491)
  • EBITDA: 7,705 (26,582)
  • EBIT: -718 (18,080)

Consolidated profit before taxes: -7,685 (11,039)

Consolidated profit after taxes: -8,216 (10,120)

  • Q3 of 2020 in EUR ,000 (same period in 2019)
  • Turnover: 41,627 (65,573)
  • Gross Profit: 12,429 (27,711)
  • EBITDA: 10,004 (23,408)
  • EBIT: 7,155 (20,582)

Consolidated profit before taxes: 4,916 (18,069)

Consolidated profit after taxes: 4,642 (17,540)

The second wave of the pandemic and the new restrictive measures in the movement of passengers are expected to lead to a decrease in traffic and revenue during the winter period 2020-2021 compared to the same period last year, while a gradual recovery of sizes is expected after Q1, 2021.

Norled Q3 Report: All Agreed Operations Have Been Carried Out Despite the Corona Challenges

By 2020 Newsletter week 50

Decrease in revenue is mainly due to changes in contract portfolio.

Revenue: -17% (Q3) and -14.6% (YTD)

Norled ended 5 contracts at year end 2019 and started 4 new contracts 1 January 2020.

  • Indre Sogn (ferries)
  • Sunnmøre (ferries)
  • Rutepakke3 Hordaland (ferries)
  • Troms (expressboats)

Increased EBITDA profitability is mainly due to changes in contract portfolio and net gain on sale of fixed assets. EBITDA: 12% (Q3) and 7.2% (YTD).

EBITDA profitability is affected by the Corona epidemic, mainly with reduced tourist related revenue in the expressboat segment.

Start of contracts on 1 January 2021:

  • Ryfylkeferjenin, Rogaland county (until 31 Dec 32)
  • Lyngensambandet, with the routes Lyngseidet-Olderdalenand Svendsby-Breivikeidetin Troms and Finnmarkcounty (until 30 April 31)

Click image for report